From the Blog
Flood Insurance in San Antonio: The $847-a-Year Cost of Buying in the Wrong Spot
The average National Flood Insurance Program policy in San Antonio costs about $847 a year, and roughly 12.1% of Bexar County's land sits inside FEMA's Special Flood Hazard Area, the 100-year floodplain that most lenders care about. Draft FEMA map updates would add roughly 5,600 more buildings in the county to flood zones. Here is the flood check every buyer should run before choosing where to make an offer.
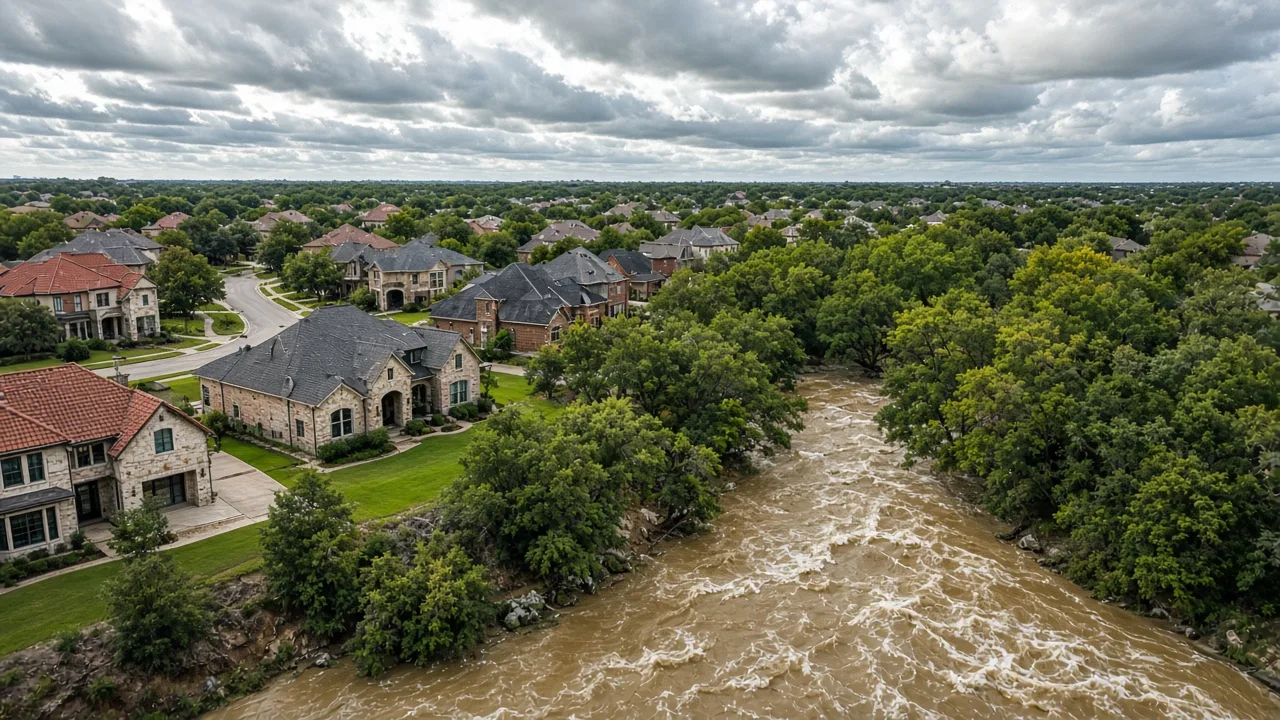
The average National Flood Insurance Program policy in San Antonio costs about $847 a year, and roughly 12.1% of Bexar County's land sits inside FEMA's Special Flood Hazard Area, the 100-year floodplain that most lenders care about. Draft FEMA map updates would add roughly 5,600 more buildings in the county to flood zones. Here is the flood check every buyer should run before choosing where to make an offer.
The Hidden Costs Nobody Mentions About Living in San Antonio TX More videos are on my channel .
The number to know first
Bexar County's own GIS data shows about 12.1% of county land lies in FEMA's Special Flood Hazard Area, the zones labeled A and AE that represent the 100-year floodplain. A separate risk model from First Street estimates about 37,970 San Antonio properties, roughly 8.7% of all properties, carry flood risk over the next 30 years. For national context, about one in five Texans lives in a floodplain, and FEMA's draft map updates for Bexar County would add roughly 5,600 buildings, including two schools, to the mapped flood zones. None of this means San Antonio is a flood disaster zone. It means flood risk is a normal part of the due-diligence list here, and the address, not the city, is what decides your exposure.
What flood insurance actually costs
Rate data published through 2025 and 2026 puts the average NFIP flood policy in Texas at roughly $779 to $791 a year, with the San Antonio average around $847. Policies in the high-risk A and AE zones average about $1,021 to $1,031 a year, while low- and moderate-risk policies run closer to $671 to $691. On a $847 annual average, that is about $71 a month, over 30 years roughly $25,000, before renewals climb. The exact quote depends on the property's flood zone, elevation, coverage amount, and deductible, which is why the honest move is getting a real quote for the address before you write an offer, not after.
Why the map matters more than the address
Flood maps are living documents. FEMA is actively redrawing Bexar County's maps, and the draft updates would add thousands of buildings to flood zones, which can change a property's insurance requirement and resale profile even if the house itself never floods. A home outside the map today can sit inside it after the next revision. That is why the check has to be official, at the parcel level, and current, not a neighborhood-level guess from a map app. When a lender sees a property in the Special Flood Hazard Area, federally backed loans require flood insurance before closing. When the property is outside it, coverage is optional, and about a third of flood claims, by FEMA's own data, come from properties outside high-risk zones, a stat worth sitting with.
The honest checklist before you buy
Add these to your due diligence on any San Antonio-area address, in this order. Each one takes minutes and can save five figures.
- Pull FEMA FIRMette for the exact parcel and check whether it falls in zone A or AE.
- Ask the seller directly whether the home has ever taken water, and ask about drainage and neighbor complaints on the street.
- Ask your lender whether the property will require flood insurance at close, and get the monthly quote before the offer.
- Check whether a FEMA map revision is pending or recently completed for that area, and what it would change.
- Request the elevation certificate if one exists, especially in older neighborhoods near creeks and the San Antonio River.
- Walk the street after rain is unrealistic on a viewing calendar, so read the drainage, retention ponds, and grading with an inspector who knows Texas soils.
This is exactly the kind of detail that separates a confident move from a surprise at closing, and it is why I run the flood, tax, and HOA checks on every shortlist before we talk numbers.
The good news: it is a price, not a verdict
A flood-zone label is not an automatic no. Homes in flood zones often trade at a discount, and in the right spot, the annual insurance cost is a line item you can budget like any other. The danger is only in skipping the check. Buyers who discover a $1,000-plus annual flood policy after their offer is accepted are the ones with buyer's remorse; buyers who price it in up front just make a smarter decision with the same house.
Written by Phyllis Domingo
REALTOR® · TX License 745926 · 100+ homes sold · Helping families move well in San Antonio and the Hill Country since long before the hard part became normal.
Have a question about this topic?
Every family's situation is different. Send me a note and I will respond personally, usually within a business day.