From the Blog
Buy and Fix With One Loan: The FHA 203(k) in San Antonio, Priced Honestly
A fixer-upper in San Antonio can be the honest path to homeownership, but the money has to work. The FHA 203(k) wraps the purchase and the renovation into one mortgage, so you are not juggling a home loan and a construction loan. The streamline version covers up to $75,000 of repairs, the full version handles structural work, and every Bexar County 203(k) loan stops at the $557,750 FHA limit. Here is how the product actually works, and where it gets people into trouble.
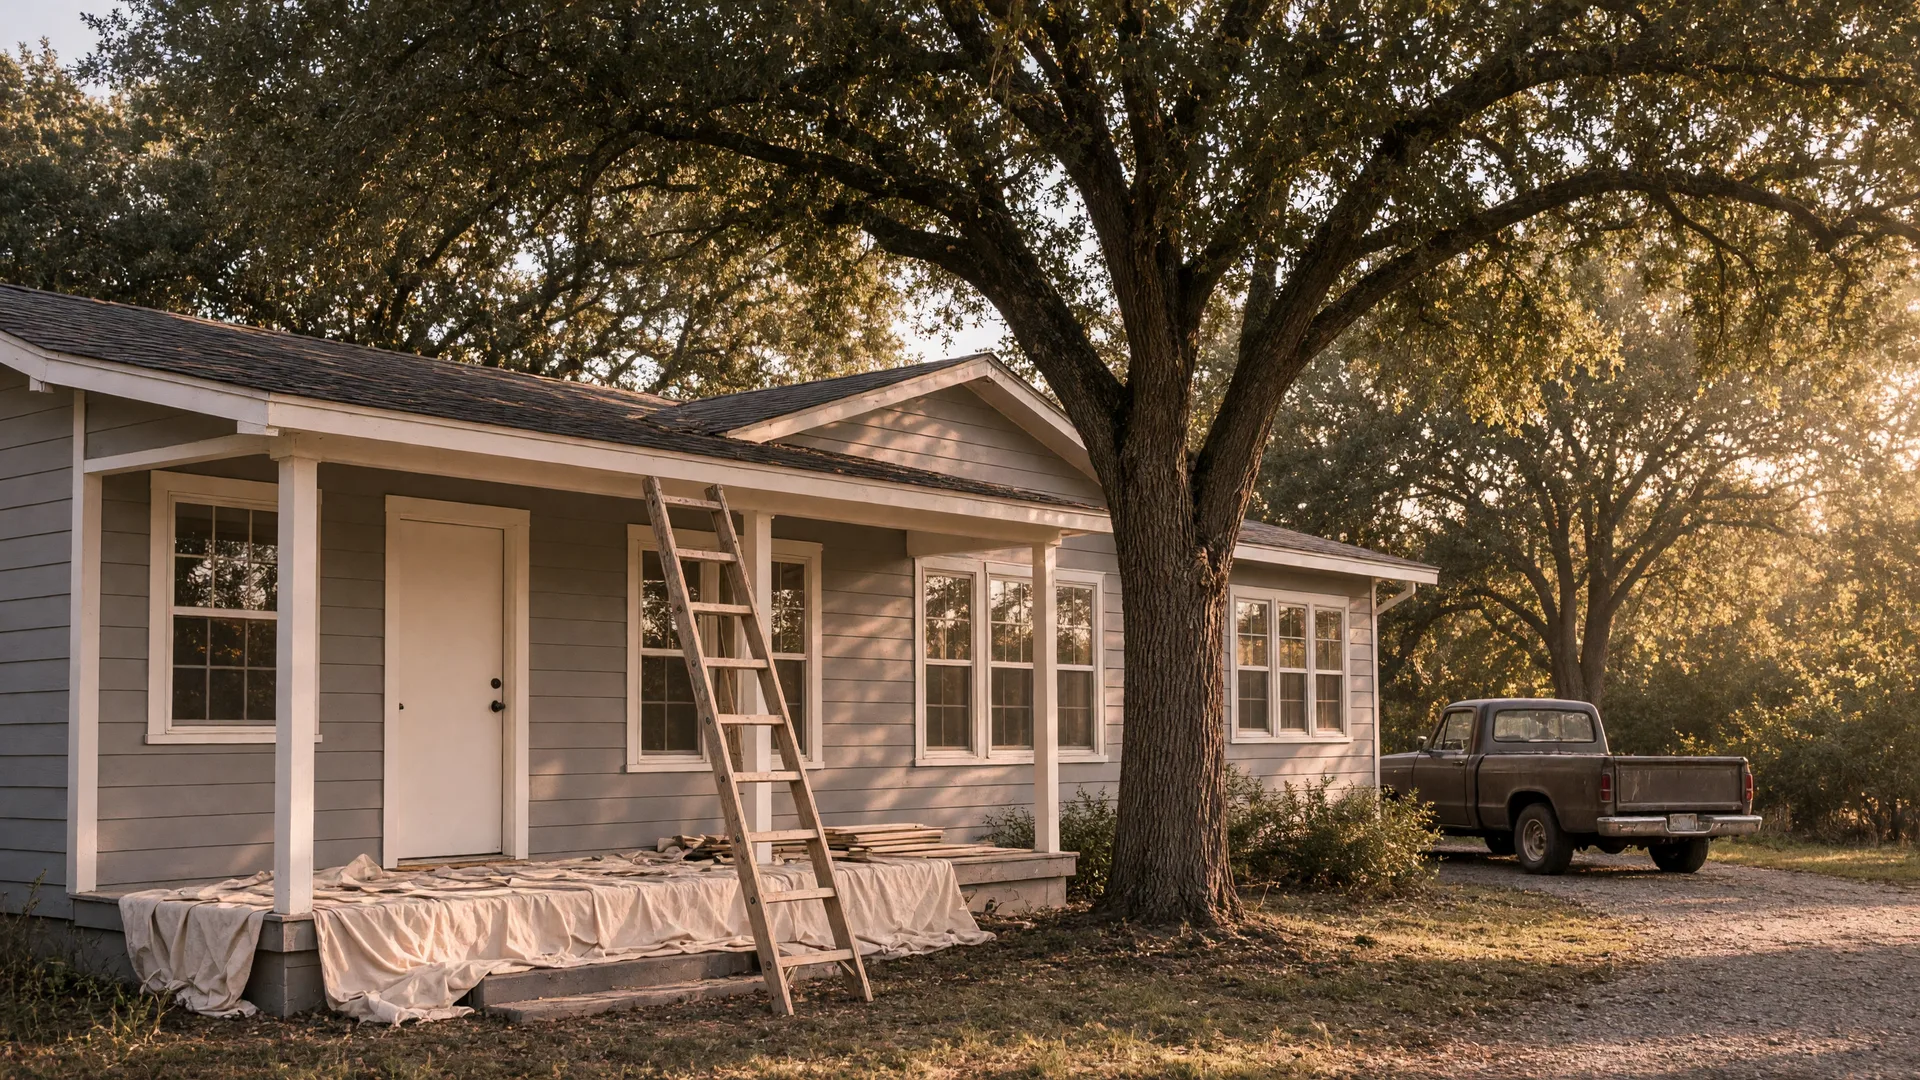
A fixer-upper in San Antonio can be the honest path to homeownership, but the money has to work. The FHA 203(k) wraps the purchase and the renovation into one mortgage, so you are not juggling a home loan and a construction loan. The streamline version covers up to $75,000 of repairs, the full version handles structural work, and every Bexar County 203(k) loan stops at the $557,750 FHA limit. Here is how the product actually works, and where it gets people into trouble.
One loan, two jobs: how the 203(k) works
With a standard FHA purchase loan, the house has to qualify on its own. With a 203(k), the loan is sized on the as-is value plus the cost of the repairs, which means the home can need work and still qualify. On a purchase, FHA insures up to 96.5% of that combined figure, and the total base loan cannot exceed the county's limit. The repair money sits in an escrow account and gets paid to the contractor in draws as the work is completed and inspected.
The $75,000 streamline, and the full version
FHA raised the streamline 203(k) repair cap from $35,000 to $75,000 in a rule that took effect November 4, 2024, so non-structural work, new flooring, a kitchen refresh, paint, appliances, and plumbing and electrical touches, fits in the faster paperwork track. Repairs over $75,000 or any structural work, moving a wall, foundation work, a major addition, requires the full 203(k), which comes with more paperwork, a HUD-approved 203(k) consultant, and a longer timeline. The math only works when the repair estimate is realistic, which is why contractors need to price the scope before you close, not after.
The $557,750 cap in Bexar County
HUD set the 2026 FHA limit for a one-unit property in Bexar County at $557,750, and the 203(k) rides on the same cap. That covers the purchase price, the rehab cost, and the financed mortgage insurance premium combined, so the cap is not the purchase price, it is the total loan. For most San Antonio fixers, both the streamline and the full version fit comfortably under it. Condos, townhomes, and two-to-four-unit properties have their own limits and rules, so confirm the number for the exact property type before you tour.
- The base loan includes the purchase plus financed repairs, capped at $557,750 for a one-unit in Bexar County.
- The repair escrow is released in draws as work passes inspection, not all at once.
- You still pay the standard FHA 3.5% down payment and monthly mortgage insurance.
Where the 203(k) trips people up
The usual failure is under-scoping the work: a contractor's bid that skips permits, or a buyer who skips the structural check and finds hidden costs after closing. Get the inspection before you set the repair budget, and build a contingency line into the scope. The full 203(k) also needs the consultant's rehabilitation plan before the loan can fund, so the timeline runs longer than a normal 30 to 45 day close. If the home only needs cosmetic work, the streamline track is the faster, cheaper choice.
Is a fixer the right call for you?
The 203(k) makes sense when you have time and a realistic budget, and when the after-improved value supports the loan. It is a bad fit when you need to move in next month, when the repair estimate is wishful, or when you are stretched so thin that one surprise wrecks the plan. If the neighborhood's cheaper resales need real work, run the full numbers with a contractor before you commit.
Frequently asked questions
Is there still a minimum repair amount for the 203(k)?
The streamline version no longer has a repair minimum after the 2024 rule change, and the old $35,000 cap moved to $75,000. The full 203(k) is for projects that exceed that streamline ceiling or include structural work.
Does the 203(k) work for condos?
Condos can use the full 203(k), but FHA limits the loan to 100% of the after-improved value for condos, and the condo project itself must meet FHA approval. Confirm both before you fall in love with a unit.
Written by Phyllis Domingo
REALTOR® · TX License 745926 · 100+ homes sold · Helping families move well in San Antonio and the Hill Country since long before the hard part became normal.
Have a question about this topic?
Every family's situation is different. Send me a note and I will respond personally, usually within a business day.